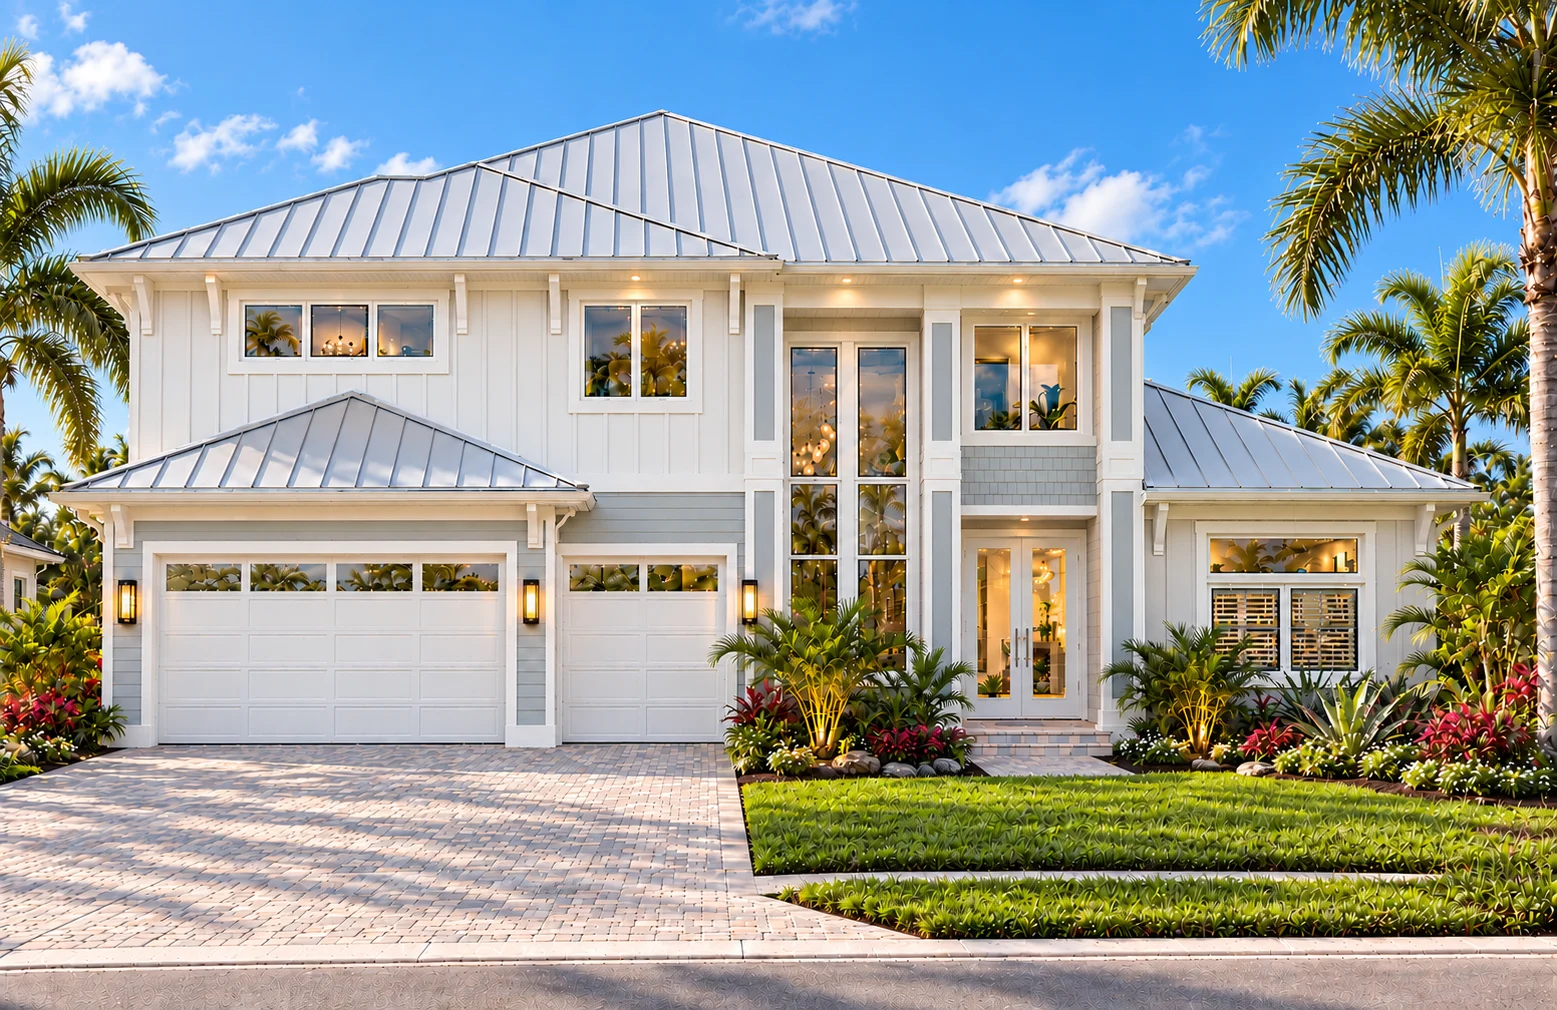
For many homeowners, the decision to build a custom home begins with a vision.
A beautiful waterfront property. A kitchen designed around family gatherings. An expansive lanai overlooking the pool. A home that finally feels like it was designed for the people living inside it.
But somewhere between imagining the home and making it a reality, another question usually enters the conversation.
What will the monthly payment actually look like?
With mortgage interest rates influencing affordability throughout Florida, many prospective homeowners are wondering whether they should build now, wait for rates to fall, or explore financing options that could make their dream home more affordable.
What many buyers don’t realize is just how dramatically a relatively small change in interest rates can affect the monthly cost of owning a home.
On a $750,000 home, the difference between two mortgage rates can amount to hundreds of dollars every month—and thousands of dollars every year.
For homeowners considering building in Cape Coral, Naples, Fort Myers, Bonita Springs, Estero, or elsewhere in Southwest Florida, understanding that difference can change the entire financial conversation.
At Conquest Builders, we believe homeowners should understand both the cost of building a home and the cost of living in it. Financing is an important part of that equation.
Table of Contents
- How Mortgage Rates Affect Custom Home Affordability
- Monthly Payment on a $750,000 Home
- How Special Mortgage Rates Can Reduce Monthly Payments
- Should You Build Now or Wait for Interest Rates to Drop?
- Understanding Construction Loan Rates in Florida
- The True Cost of Owning a Custom Home
- Using Financing Savings to Build a Better Home
- The Conquest Builders Approach
- Frequently Asked Questions
- A Better Home Starts With a Better Financial Decision
How Mortgage Rates Affect Custom Home Affordability in Southwest Florida
Mortgage rates influence much more than the total interest paid over the life of a loan.
They influence what a homeowner can comfortably afford every month.
For someone financing several hundred thousand dollars, even a modest change in interest rates can create a substantial difference in monthly payments.
That difference becomes especially meaningful when building a custom home, where homeowners are balancing construction costs, property expenses, architectural decisions, and the quality of materials being incorporated into the finished residence.
A lower mortgage rate may allow a homeowner to build the home they actually want rather than compromising on important features simply to reach a particular monthly payment.
Of course, the interest rate is only one part of the financing equation. Down payment, loan amount, closing costs, lender fees, loan type, credit qualifications, and property-specific expenses also affect affordability.
But understanding the impact of interest rates is an excellent place to begin.
How Much Is the Monthly Payment on a $750,000 Home?
Let’s look at an example that illustrates just how important mortgage interest rates can be.
Imagine purchasing or building a home with a total price of $750,000.
With a 20% down payment of $150,000, the remaining mortgage would be $600,000.
Now compare two hypothetical 30-year fixed mortgage rates.
At an illustrative interest rate of 7.37%, the monthly principal-and-interest payment would be approximately $4,143.
At an illustrative special interest rate of 4.875%, the monthly principal-and-interest payment would fall to approximately $3,175.
That’s a difference of approximately $968 every month.
Over twelve months, that represents approximately $11,600 in lower principal-and-interest payments.
These rates are examples used to demonstrate financing mathematics. They are not verified current market quotes or a representation that Conquest Builders currently offers either rate.
These payments also exclude property taxes, homeowners insurance, flood insurance where applicable, HOA assessments, closing costs, points, lender fees, and other ownership expenses.
Still, the difference is substantial.
Nearly $1,000 per month can change the way a homeowner approaches an entire custom home project.
How Special Mortgage Rates Can Reduce Monthly Payments
Most buyers naturally focus on negotiating the purchase price of a home.
And price certainly matters.
But financing can sometimes create a larger monthly difference than homeowners expect.
Special mortgage-rate programs, lender incentives, and builder-assisted financing arrangements may provide opportunities to reduce borrowing costs for qualified buyers.
The important question is not simply whether a lender advertises a lower interest rate.
It’s what that rate actually costs and how long it lasts.
Some reduced rates are achieved through discount points or upfront financing contributions. Others may involve temporary buydowns that reduce payments for an introductory period before returning to the permanent note rate.
These arrangements can be valuable, but homeowners should understand the annual percentage rate, closing costs, qualification requirements, and complete loan terms before comparing offers.
When a favorable permanent rate is available on reasonable terms, the monthly savings can be significant.
And that creates an interesting opportunity for someone building a custom home.
Instead of spending more money simply to carry the mortgage, they may have greater financial flexibility to invest in the quality of the home itself.
Should You Build Now or Wait for Interest Rates to Drop?
This may be one of the most common questions prospective homeowners ask when mortgage rates become a major news topic.
Should we build now?
Or should we wait?
The challenge is that nobody can reliably predict where mortgage rates will be six months or a year from now.
Rates may decline. They may remain relatively stable. They may increase.
Meanwhile, other parts of the custom home equation continue changing.
Desirable lots may become more expensive or unavailable. Construction materials and labor costs can change. Design requirements may evolve. And homeowners may find themselves postponing a home they otherwise could comfortably afford.
That doesn’t mean everyone should rush to build.
It means the decision should be based on realistic financing scenarios rather than an attempt to perfectly time the mortgage market.
For some homeowners, waiting will make sense. For others, beginning the design and planning process while evaluating financing options may be the better approach.
Because even after the decision to build has been made, architecture, engineering, permitting, selections, and construction all require time.
The most productive first step is understanding what you want to build, what it is likely to cost, and what financing options may be available.
Understanding Construction Loan Rates in Florida
Financing a custom home can be different from purchasing an existing property.
With an existing home, the buyer typically obtains a mortgage secured by a completed residence.
With new construction, the lender may be financing a home that has not yet been built.
Some homeowners use a construction loan followed by permanent mortgage financing. Others choose a construction-to-permanent loan, which can combine the construction phase and long-term mortgage into a single financing arrangement.
Construction loan interest rates, draw schedules, down-payment requirements, interest-only payment provisions, and rate-lock terms can vary significantly between lenders.
This makes it important to understand when the rate is established, how interest is charged during construction, and what happens when the home is completed.
A favorable advertised mortgage rate may not automatically apply to a construction loan or construction-to-permanent financing.
For homeowners planning a custom home in Cape Coral, Naples, Fort Myers, or elsewhere in Southwest Florida, these conversations should happen early enough that financing supports the design and construction process rather than complicating it.
The True Cost of Owning a Custom Home
A mortgage payment is only one part of the cost of owning a home.
Two homes with the same square footage and similar purchase prices can have very different long-term ownership expenses.
Windows, insulation, roofing, air sealing, HVAC design, waterproofing, and other construction decisions can influence comfort, energy consumption, maintenance, and durability.
That is especially important in Southwest Florida, where homes face intense sunshine, humidity, heavy rain, coastal exposure, and seasonal storms.
A lower construction price may be attractive today, but homeowners should also consider what the home may cost to operate and maintain over the years ahead.
We explore this concept in greater detail in our article on building a better quality of life through higher-performing home construction.
Understanding these differences is one reason we encourage homeowners to compare more than the initial price per square foot.
Our guide to the cost of building a house and choosing the right home builder in Southwest Florida explains why two homes that look similar may represent very different long-term investments.
Using Financing Savings to Build a Better Home
Imagine having several hundred dollars more available each month because of a favorable mortgage rate.
For some homeowners, that additional flexibility may simply make the monthly budget more comfortable.
For others, it may create an opportunity to invest in improvements they might otherwise have eliminated during design.
Better windows. Improved insulation. Thoughtful lighting. Custom cabinetry. More functional storage. A larger covered lanai. Better architectural detailing.
These decisions can influence how a home looks, feels, and performs every day.
But we don’t believe homeowners should spend more simply because financing makes it possible.
We believe they should understand where the additional investment creates meaningful value.
For more ideas, explore our guide to luxury home features worth the investment.
And if you’re planning to build in Naples, our article on what it costs to build a luxury custom home in Naples, Florida explains how construction specifications, site conditions, and finish selections influence the final investment.
The Conquest Builders Approach
At Conquest Builders, we believe building a beautiful home and making intelligent financial decisions should go hand in hand.
We care about architecture, cabinetry, stone, lighting, ceiling details, and the finishes that create an exceptional living environment.
But we also care about what homeowners may never see once construction is completed.
The foundation. The structure. The insulation. The roof. The windows. The waterproofing. The mechanical systems.
Those decisions can influence the comfort, durability, efficiency, and long-term ownership experience of a home.
When favorable financing is available, it can help homeowners achieve a better balance between their monthly payment and the quality of the home they want to build.
Our goal is not simply to build the most expensive home possible.
It’s to help homeowners understand where their money creates the greatest value.
Frequently Asked Questions
What are current mortgage rates for custom homes in Southwest Florida?
Mortgage rates change frequently and depend on the lender, loan program, borrower qualifications, property type, down payment, and other factors. Construction loans